Three years ago, I almost lost an eleven-thousand-dollar milestone with a tech startup in London. I had delivered the complete product architecture, hit every technical spec, and logged off for the weekend feeling victorious.
By Monday morning, my invoice was sitting in their accounting queue. Two weeks later, I got an email saying their domestic bank couldn’t verify my overseas routing instructions.
When the money finally landed three weeks after that, it was missing four hundred and eighty dollars. Nobody could tell me where that money went. My bank blamed their bank, and their bank blamed a intermediary institution somewhere in Frankfurt.
Look, if you work with international clients long enough, this story becomes your daily reality. You trade high-value creative or technical labor across borders, but you operate in a financial fog.
You worry about whether the client will actually release final funds once you deliver. You worry about exchange rate gouging. And you worry about losing hundreds of dollars in hidden wire fees before the cash even hits your checking account.
I wrote this guide to fix that exact problem. I will show you how to lock down global contracts, protect your deliverables, and stop paying punitive bank fees just to get paid for your own work.
Table of Contents
The $11,000 Ghost Invoice : A Real-World Case Study
Let’s break down what actually happened with my London client, because it reveals the exact financial architecture that catches most independent contractors off guard.
I had structured the contract as a standard 50/50 split. Fifty percent upfront, and fifty percent upon final code migration.
When I delivered the final code repository, I transferred full ownership rights before the final wire cleared. That was my first major mistake.
The client wasn’t trying to scam me. They were a legitimate startup with real funding. But their corporate account was tied to a traditional UK clearing bank that routed all international outgoing transfers through two separate correspondent banks.
Based on the bank records and explanations we received, this was our best reconstruction of the shortfall:
Important: The exact allocation of every dollar between the sending bank, intermediary institutions, and receiving bank was never independently confirmed by every institution in the payment chain. The figures below are therefore a reconstruction of the transaction, not a universal fee schedule.
The client claimed they sent eleven thousand dollars. My bank statement showed ten thousand two hundred and forty-five dollars.
Neither of us wanted to swallow the difference. The relationship turned sour, communication broke down, and I spent three weeks acting as my own forensic accountant instead of taking on new client work.
The Takeaway : Cross-border payment friction isn’t just an expense issue. It’s a legal and trust vulnerability that directly threatens your cash flow and client relationships.
Section 1 : Cross-Border Settlement Blindspots
When you contract within your home country, you enjoy an invisible safety net. Small claims court exists, local contract law is predictable, and domestic ACH or SEPA networks settle payments quickly for pennies.
The moment your work crosses an international border, that safety net disappears.
Here are the three settlement blindspots that expose global freelancers to massive risk:
1. Jurisdictional Enforceability Limits
If a client in Singapore, Germany, or another foreign jurisdiction refuses to pay your final invoice, the recovery process can become more complicated because the client’s location, assets, governing law, jurisdiction clause, and available enforcement mechanisms may all differ from your own.
A foreign judgment does not automatically mean that arbitration is required, and there is no universal dollar threshold at which formal legal action becomes worthwhile or unworthwhile. Depending on the contract and jurisdictions involved, potential routes can include negotiation, court proceedings, arbitration, judgment enforcement, or other local remedies.
Before escalating an international payment dispute, review the contract’s governing-law and jurisdiction provisions, identify where the client and relevant assets are located, and obtain advice from a lawyer qualified in the jurisdictions that actually matter to the dispute.
Existing internal link: Keep your current link on “when it is officially time for a freelancer to take legal action” exactly where it is.
Before taking drastic measures on unpaid work, read about when it is officially time for a freelancer to take legal action to evaluate your real recovery odds.
2. The Intermediary Bank Void
Most traditional international transfers rely on the SWIFT network. SWIFT doesn’t actually move money; it sends secure messaging between financial institutions.
A payment may pass through one or more correspondent institutions when the sending and receiving banks do not have a direct settlement relationship. Depending on the payment route and the terms of the institutions involved, intermediary or receiving-bank charges can reduce the amount ultimately credited to the beneficiary.
The exact number of intermediaries and the charges applied are transaction-specific, so neither the sender nor recipient should assume a particular fee amount without checking the relevant bank and payment instructions.
3. Asymmetric Ownership Transfers
The biggest operational risk is releasing final source code, high-resolution design assets, or live site access before final funds settle.
If you transfer full intellectual property rights before payment clears your account, you lose all financial leverage.
If you find yourself stuck in this scenario with digital work, review this guide on how to handle a client who stole your website code or read how developers can handle clients who haven’t paid after a website migration.
Section 2 : Digital Escrow Platforms Analyzed
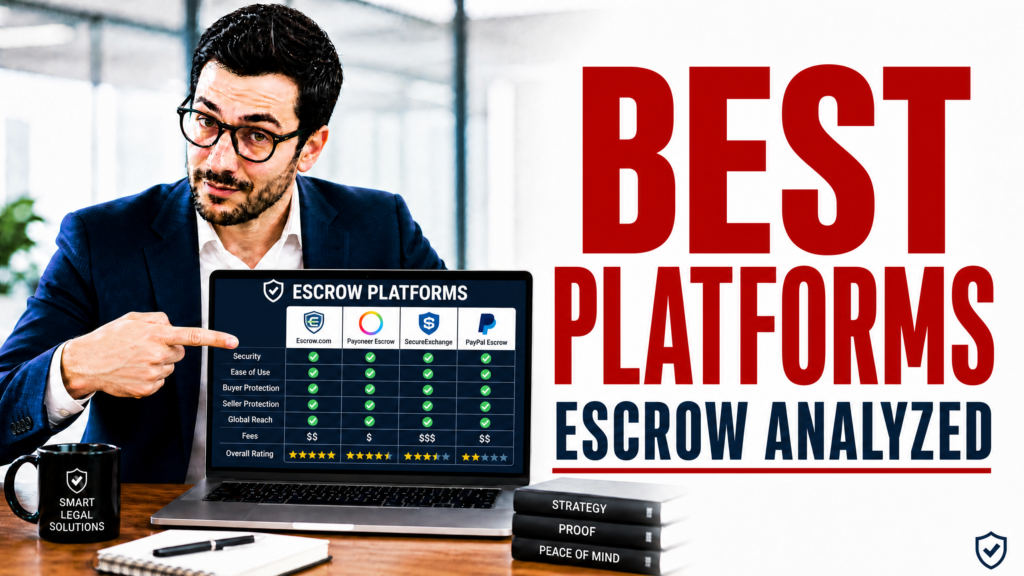
To eliminate cross-border payment risk, you need an architecture that holds funds securely before you start working and releases them automatically upon milestone approval.
Not all payment platforms are created equal. Let’s compare the three heavyweights in global settlement: Wise, Escrow.com, and Stripe.
Wise (formerly TransferWise)
Wise isn’t a traditional escrow service. Depending on your country, account type, currency, and eligibility, Wise may provide currency-specific account details that allow clients to send payments through local payment rails rather than using a traditional international SWIFT transfer.
For example, Wise currently describes local receiving details for certain currencies, including USD, EUR, and GBP, but the available currencies, payment methods, receiving fees, limits, and account features vary by region and can change over time. A domestic payment route may reduce or avoid some international transfer costs, but it should not be treated as a reduce the risk that every bank fee will disappear.
Best for: Established client relationships where trust exists and you want to explore potentially lower-cost payment routes than traditional international wires.
Drawback: Wise account details do not create an escrow relationship or automatically provide milestone-based protection against non-payment. Receiving fees, correspondent-bank charges, conversion costs, eligibility requirements, and payment limits may still apply.
Important: Check the provider’s current pricing, available account details, supported currencies, and receiving rules for your specific country before putting payment instructions into a contract.
- Best for: Established client relationships where trust exists, but high wire and exchange fees are eating profits.
- Drawback: Offers no built-in dispute resolution or conditional holding of funds.
Escrow.com
Escrow.com is a dedicated escrow service rather than an ordinary payment processor. Its transaction structure is designed to hold funds while the parties complete the agreed transaction steps.
For a freelance or digital-services arrangement, the exact deposit, inspection, approval, release, refund, and dispute procedures depend on the transaction structure and the provider’s current terms. Do not assume that every transaction automatically follows the same release timetable or dispute mechanism.
Best for: Higher-value international projects where the parties want a third-party escrow structure rather than relying solely on an ordinary invoice or bank transfer.
Drawback: Escrow introduces additional fees, onboarding requirements, transaction conditions, and dispute procedures that should be reviewed before the contract is signed.
Important: Verify the provider’s current fees, eligibility requirements, dispute procedures, release conditions, supported payment methods, and applicable terms before incorporating escrow into a contract.
- Best for: High-value international projects ($5,000 to $100,000+) with unfamiliar or non-vetted overseas clients.
- Drawback: Higher fee structure and rigid compliance checks that can slow initial onboarding.
Stripe (with Custom Milestones or Invoicing)
Stripe is a payment-processing platform that can support cards and other payment methods, subject to the country, account, currency, and payment method available to the merchant.
Standard payment processing should not be confused with legal escrow. You can structure invoices or payment schedules around project milestones, but that does not automatically mean the funds are being held in a neutral escrow arrangement.
Payment disputes can also remain possible. A cardholder may have dispute or chargeback rights under the applicable payment-network rules, processor terms, and relevant law.
Best for: Retainers, recurring services, and smaller or medium-sized project payments where ordinary payment processing is appropriate.
Drawback: Payment processing does not by itself eliminate non-payment, refund, fraud, or chargeback risk.
Important: Review the current processor pricing, supported payment methods, dispute rules, and country-specific terms before selecting Stripe for a cross-border project.
- Best for: Retainers, ongoing digital services, and low-to-medium project milestones.
- Drawback: Chargeback risks remain present if a client disputes a credit card charge through their issuing bank.
The Global FinTech Comparison Matrix
Here is an objective side-by-side comparison of how these clearing mechanisms perform across key operational metrics:
The Global Payment Method Comparison Matrix
| Payment Method | True Escrow? | Main Cost Drivers | Main Risk | Best Use Case |
|---|---|---|---|---|
| Dedicated Escrow Service | Yes, where the transaction is structured as escrow | Provider fee, payment method, currency conversion, transaction terms | Fees and dispute/release conditions | Higher-value projects or unfamiliar clients where payment security is a priority |
| Wise / Multi-Currency Account | No | Transfer fee, currency conversion, receiving fees, and possible correspondent-bank charges | No automatic milestone escrow protection | Established clients where a lower-friction payment route is appropriate |
| Stripe / Card Processing | No | Processing fee, currency conversion, payment method, disputes/chargebacks | Payment disputes and processor rules | Smaller projects, retainers, and clients comfortable with card payments |
| Traditional International Bank Wire | No | Sending-bank fee, intermediary charges, receiving-bank fee, FX spread | Unexpected deductions, delays, and payment-routing issues | Established commercial relationships where bank wires are operationally convenient |
Important: This table intentionally avoids universal percentage figures because actual costs vary by country, currency, payment method, account type, transaction size, and provider. may check the current provider pricing and payment terms before quoting a fee to a client.
Important: Payment Fees and Rules Change
Payment providers, banks, payment networks, and regulators can change their fees, supported currencies, account features, transaction limits, dispute procedures, and compliance requirements.
The examples and estimates in this guide are therefore intended for planning and comparison, not as reduce the risk quotes or legal conclusions. Before incorporating a payment method, fee allocation, escrow arrangement, or regulatory assumption into a live contract, verify the provider’s current terms, the actual payment route, and the law applicable to your transaction.
Interactive International Fee & Risk Calculator
International Fee & Risk Calculator
Estimate the potential effect of transfer fees, intermediary charges, and foreign-exchange costs on your net payment before signing an international agreement. **Important:** The calculator uses illustrative assumptions rather than guaranteed provider pricing. Actual costs vary by bank, provider, currency, payment method, account type, transaction route, and applicable fees.
SWIFT Bank Wire
High RiskWise Local Clearing
Medium RiskEscrow.com
Lowest RiskStripe Global
Medium RiskUse this calculator to compare total transaction costs and settlement risks across different international payment methods before signing your next global contract.
Section 3 : Minimizing Wire Intermediary Fees
If you or your client insist on using direct bank-to-bank wires, you must configure the transfer instructions to prevent unexpected deductions.
Understanding SWIFT Fee Codes : OUR, BEN, and SHA
Every SWIFT wire transfer carries a specific fee-handling instruction tag. Understanding these three letter codes will instantly save you hundreds of dollars:
OUR: The sender requests that the transfer charges be borne by the sender. This is intended to reduce deductions from the beneficiary’s payment, but it should not be described as an absolute reduce the risk that the exact invoice amount will arrive.
BEN: Charges are borne by the beneficiary, with applicable charges deducted from the amount received.
SHA (Shared): Charges are generally shared between sender and beneficiary according to the payment route and applicable bank terms.
| Code | Who Pays Intermediary Bank Fees? |
|---|---|
|
OUR
Recommended
|
Client covers 100% of fees. You receive your full net invoice amount without unexpected deductions. |
|
BEN
Avoid
|
You pay 100% of fees. All bank charges and intermediary lifting costs are subtracted directly from your payout. |
|
SHA
Default
|
Shared split. Client pays their sender bank fee, while you absorb all intermediary and receiving bank charges. |
When the wire arrives light, they will argue they fulfilled their legal obligation by sending the full amount from their account.
How to Draft Fee-Protection Clauses
To avoid this trap, add explicit payment routing clauses to your agreement.
Your contract should clearly state:
“All international bank transfer fees, including intermediary bank lifting charges and foreign exchange conversion costs, are the sole responsibility of the Client. Payments must be issued using SWIFT fee instruction OUR to ensure full invoice settlement.”
If you are setting up contract terms, make sure you align this with proper payment windows. See my guide on Net 15 vs Net 30 payment terms to structure your billing schedule correctly.
Important: A contractual fee-allocation clause determines which party is responsible for the economic cost between the parties. It does not necessarily control what a sending, intermediary, or receiving bank deducts during the payment process. If the amount received is less than the contractual amount, the agreement may provide a basis for seeking the shortfall from the client, subject to the governing law and contract terms.
Section 4 : Constructing International Pay Schedules
Securing global contracts isn’t just about choosing the right software platform. It requires structuring payment milestones that minimize your exposure at every phase of production.
Never work under a single massive payment at the end of an international project. If a client ghosted you on local soil, you could drop by their office or send a demand letter. Overseas, ghosting costs them nothing.
If you ever find yourself dealing with radio silence after sending an invoice, read my step-by-step breakdown on what to do when a client ghosted after receiving an invoice.
Here is how to structure a bulletproof 4-stage international pay schedule:
Stage 1 : The Deposit (30% – 50%)
- Mechanism: Direct local transfer or credit card via Wise/Stripe.
- Goal: Cover your base operating costs before committing calendar hours.
- Rule: Zero project work begins until these funds clear into your bank account.
Stage 2 : Interim Deliverables (30%)
- Mechanism: Wise local transfer or digital escrow milestone release.
- Goal: Keep cash flow moving while validating client responsiveness.
- Rule: If the client delays payment approval beyond 5 business days, issue a formal pause notice.
If a client starts dragging their feet mid-project, learn how to use the notice of suspension of services without destroying the relationship.
Stage 3 : Staging and Testing (30%)
- Mechanism: Held in Escrow or hosted entirely on your private control server.
- Goal: Allow complete client review without surrendering control of raw source files, design assets, or database access.
- Rule: Client tests functionality inside your sandbox environment only.
Protect your work during presentation by using techniques like watermarking UI/UX deliverables without ruining client reviews.
Stage 4 : Final Migration & IP Transfer (10%)
- Mechanism: Escrow release according to the provider’s agreed milestone, inspection, approval, and release procedure after the required delivery conditions are satisfied.
- Goal: Smooth final sign-off with minimal remaining financial risk.
- Rule: Unless the contract expressly provides otherwise, structure the IP assignment or licence so that the client’s rights become effective only after the payment required for that transfer has been received and cleared. The exact wording should be adapted to the governing law and the type of intellectual property involved.
If a client pushes for work outside the original project scope before releasing final funds, refer to my guide on charging for scope creep without losing the client.
United States vs. Global Legal Protections: Regulatory Realities
Understanding the governing legal frameworks across primary regulatory jurisdictions ensures you draft contracts that courts and arbitrators actually enforce.
1. United States Framework
1. United States Framework
For U.S. commercial funds transfers, UCC Article 4A can be relevant to payment orders and certain rights and obligations arising from funds transfers. Its application depends on the transaction, the parties involved, the applicable state law, and the specific facts surrounding the payment order.
For qualifying consumer remittance transfers, Regulation E’s Remittance Transfer Rule, 12 CFR Part 1005, Subpart B, contains disclosure, error-resolution, cancellation, and related requirements. These protections are not a universal rule governing every business-to-business international payment made by a freelancer or company.
Practical takeaway : Do not assume that a U.S. payment rule automatically governs your international commercial invoice. Identify the parties, payment method, applicable law, and nature of the transaction before relying on a particular statutory protection.
Source-check note : Regulatory requirements can change. Verify the current text and applicability of the relevant rule before relying on it for a live transaction.
UCC Article 4A sets clear statutory rules regarding payment orders, verification procedures, and liability for delayed or misrouted bank wires.
When dealing with consumer-facing or individual remittance transfers, the Consumer Financial Protection Bureau (CFPB) enforces the Remittance Transfer Rule under Regulation E (12 CFR Part 1005).
This rule mandates that payment providers disclose upfront fees, exchange rates, and foreign taxes before funds are sent.
2. United Kingdom & European Union Framework
In the United Kingdom, payment services are subject to a regulatory framework that includes the Payment Services Regulations 2017, together with rules and supervisory requirements applicable to regulated payment and electronic-money firms. The precise obligations depend on the regulated activity, provider, payment service, and circumstances involved.
In the European Union, the payment-services framework includes rules concerning payment services, security requirements, consumer protections, and payment execution. Strong Customer Authentication (SCA) is relevant to certain payment transactions, but it should not be treated as a universal protection against non-payment under a freelance services contract.
Practical takeaway: Payment regulation and contract enforcement are different questions. A regulated payment provider may have obligations concerning how a payment service operates, while the underlying freelancer-client dispute may still depend on the contract, governing law, jurisdiction, and applicable commercial law.
Important: UK and EU payment-services rules are subject to legislative and regulatory developments. Verify the current rules and their application to the specific transaction before relying on them as a contractual protection.
Cross-Jurisdiction Summary
| Region | Relevant Regulatory Framework | What It May Address | What Freelancers Should Not Assume |
|---|---|---|---|
| United States | UCC Article 4A; Regulation E for qualifying remittance transfers | Payment orders, certain funds-transfer rules, and consumer remittance protections where applicable | That every international business invoice receives Regulation E protection |
| United Kingdom | Payment Services Regulations 2017 and applicable FCA framework | Regulation of qualifying payment services and payment institutions | That payment regulation automatically reduce the risk recovery of an unpaid commercial invoice |
| European Union | EU payment-services framework and applicable national implementation | Payment services, security requirements, and related payment protections | That payment-security rules eliminate contractual or cross-border enforcement risk |
Important: The applicable rules depend on the parties, payment provider, transaction type, jurisdiction, and date of the transaction. Treat this table as a starting point for research, not a substitute for jurisdiction-specific legal advice.
Evidence Checklist for Global Client Onboarding
Before executing any work for an overseas client, compile this legal and financial evidence package. Store these records in an isolated secure cloud folder.
- [ ] Verified Business Entity Record: Certified company registration number from the client’s home jurisdiction (e.g., UK Companies House, US SEC/State Registry).
- [ ] Signatory Authorization Proof: Written evidence that the individual signing the agreement has authority to bind the company legally.
- [ ] Executed Written Contract: Signed agreement identifying the governing law, dispute-resolution mechanism, payment method, responsibility for transfer costs, payment milestones, and when ownership or licensing rights become effective. If an international wire is used, document the agreed payment instructions rather than assuming that an OUR instruction alone reduce the risk the net amount received. If you lack a formal contract, review can you sue a client without a contract.
- [ ] Written Scope Sign-off: Clear documentation of project requirements exchanged via email or project management tickets. Learn how to turn email trails into legally defensible invoice statements.
- [ ] Escrow Deposit Confirmation: Verification from the platform that milestone funds are fully deposited and secured before starting work.
- [ ] Staging Environment Logs: Date-stamped access records showing client review and testing activities inside your private server.
International Client Risk Assessment Matrix on How to Secure Global Projects
Evaluate every prospective international client against this risk framework before finalizing payment terms:
| Risk Profile | Client Attributes | Recommended Payment Architecture | Permissible IP Transfer Timing |
| LOW RISK | Registered enterprise (>50 employees), repeat history, domestic clearing account available. | Wise local ACH/SEPA transfer or Net-15 invoicing with late fee terms. | Upon receipt of the contractually required payment for the relevant milestone, subject to the governing IP and licensing provisions. |
| MEDIUM RISK | Mid-stage startup, clear online footprint, working across standard regulatory zones (US/UK/EU). | 50% upfront deposit + Stripe/Wise milestone clearance before final deployment. | Strictly upon receipt of cleared funds in your bank account. |
| HIGH RISK | Newly formed entity, anonymous contacts, non-standard jurisdiction, high project value (>$10k). | A reputable escrow arrangement or another payment structure that secures sufficient funds before substantial delivery. Select the provider and funding structure after reviewing fees, jurisdiction, transaction size, payment method, dispute procedures, and provider terms. | After the payment or escrow release required under the contract has been verified, subject to the governing IP clause and applicable law. |
Quick Decision Section: How to Choose Your Payment Setup
Need to make a fast call on an upcoming international contract? Use this framework as a starting point rather than a rigid rule.
Is the project high-value and the client new or insufficiently vetted?
YES: Consider a reputable escrow arrangement or another structure that secures payment before substantial delivery. Compare the provider’s current fees, release procedures, dispute mechanism, supported payment methods, and applicable terms before selecting it.
NO: Move to Step 2.
Does the client have access to a suitable domestic payment route in the relevant currency?
YES: Consider a multi-currency payment provider or local bank-transfer route if it is available to you and the current fees and account terms make economic sense.
NO: Move to Step 3.
Is the client insisting on a traditional international bank wire?
YES: Put the payment instructions, responsibility for transfer costs, currency, payment amount, and expected payment date in writing. If the parties agree to an OUR instruction, treat it as a contractual payment instruction rather than a reduce the risk that no deduction can ever occur.
NO: Consider a payment processor or other method appropriate for the project size, client profile, currency, and transaction risk.
The right payment structure depends on more than invoice value alone. Consider client identity, payment history, project stage, jurisdiction, contract terms, IP value, available enforcement options, fees, and the amount of work you would lose if the final payment failed.
If a client demands custom terms like Net-60 or attempts to add unexpected legal agreements before paying, read how to handle a client who retrospectively demands an uncontracted NDA before clearing an invoice.
Frequently Asked Questions
Who should pay international escrow transaction fees ?
There is no universal rule requiring escrow fees to be split 50/50. The parties can allocate the cost contractually, subject to the escrow provider’s terms and applicable law.
For a high-risk project, a freelancer may decide that paying some or all of the fee is commercially worthwhile, but escrow should not be described as a reduce the risk of payment or cash flow. Review the provider’s current fee schedule and release/dispute conditions before deciding how to allocate the cost.
Can a client issue a chargeback on international digital escrow ?
Do not assume that an escrow arrangement makes every payment dispute or reversal impossible. The available remedies depend on the escrow provider, funding method, transaction structure, provider terms, payment-network rules, and applicable law.
Before relying on escrow for a high-value project, review the provider’s current rules concerning funding, release, refunds, disputes, chargebacks, fraud claims, and contested transactions. A standard card payment processed through a payment processor may also remain subject to the applicable dispute and chargeback framework.
What happens if a client refuses to release escrow funds after I deliver ?
The answer depends on the escrow provider’s current transaction terms and dispute procedure. A well-structured escrow arrangement may provide a defined process for handling a client’s refusal to approve a milestone, but you should not assume that every provider uses the same dispute mechanism or that an arbitrator will automatically release funds.
Keep the signed agreement, milestone specifications, delivery records, testing evidence, approval communications, repository history, and other contemporaneous evidence. If a dispute arises, those records may be important in whatever dispute or review process the applicable provider and contract require.
How do I avoid foreign exchange (FX) conversion markup losses ?
Consider whether a supported multi-currency account would give you more control over when and how you convert foreign-currency receipts. Depending on the provider, currency, country, account type, and payment route, holding funds in the received currency may allow you to delay conversion rather than automatically accepting a bank’s conversion rate.
However, a multi-currency account does not necessarily eliminate FX costs. Providers may apply their own exchange rates, conversion fees, receiving charges, or other costs. Compare the actual amount you expect to receive and the amount you expect to retain after conversion rather than comparing headline fee percentages alone.
What if an international client insists on paying via traditional bank wire ?
You can accept a traditional international wire if the payment route is commercially acceptable and the contract clearly identifies the payment amount, currency, payment deadline, and responsibility for transfer costs.
If the parties agree to use the SWIFT OUR instruction, document that instruction in the contract and payment instructions. However, do not describe OUR as a reduce the risk that the exact invoice amount will reach your account. Bank charges, intermediary practices, receiving-bank fees, currency conversion, and the specific payment route can affect the final amount credited.
For high-value transactions, confirm the expected receiving amount and applicable charges with the relevant financial institutions before relying on the payment method.
Author Box & Professional Disclaimer
Adv. Sagar Haribhau Shirsat is an Indian advocate who writes about freelancer contracts, unpaid invoices, commercial payment disputes, and practical legal risk management for independent professionals working with domestic and international clients.
His work focuses on translating complex payment and contract issues into practical steps freelancers can use to document transactions, structure payment terms, preserve evidence, and reduce avoidable recovery risks.
Connect via his Official Professional LinkedIn Profile.
Disclaimer: This article is provided for general educational and risk-management information. It is not a substitute for legal, financial, tax, banking, or regulatory advice tailored to your circumstances.
International payment rules, provider terms, banking practices, tax treatment, and enforcement procedures vary by jurisdiction and can change over time. References to particular payment providers, financial products, regulations, or payment methods do not constitute an endorsement or reduce the risk of their availability, pricing, suitability, dispute process, or legal effect.
For a specific cross-border contract or payment dispute, consult a lawyer qualified to advise on the relevant jurisdiction and applicable law.